


Companies — both public and private — strive to build boards that are instrumental to long-term value creation. But boards often feel they have to follow somebody else’s playbook. The goal of this paper is to share insights from interviews with board directors, CEOs, and experts along with a series of tools that boards can use to create their own playbook for success.
Companies have unique strategies, cultures, and strengths and weaknesses. As companies grow, and especially if they shift from private to public markets, they encounter a set of norms that governance experts expect them to follow. Some of these norms are listing requirements or laws that companies must follow, but many are simply norms – somebody else’s playbook.
Over time, the company’s competitive environment will undoubtedly change, and the board and management will need to adapt their strategy to thrive. Just as circumstances and challenges evolve, so do boards. There is no single standard playbook that works across all companies or even the same company over time.
Rather than running the same play, organizations that thrive over extended periods develop differentiated governance models that align with their specific strategy and adapt as circumstances evolve. The alignment between the board, executive leadership, and strategic vision is often the linchpin in sustained corporate performance.
Our research, based on extensive interviews with board directors, CEOs, and governance experts, reveals a fundamental challenge: while directors and executives broadly acknowledge the importance of strategic alignment, many companies have not achieved it.
The most effective long-term boards calibrate their orientation across three critical dimensions:
- Strategic Time Horizon: Aligning board perspectives with the company’s investment cycles and growth trajectory
- Risk-Growth Balance: Establishing an appropriate equilibrium between opportunity pursuit and risk management
- Board-Management Relationship: Structuring governance to provide both partnership and appropriate oversight
Borrowing from sports terminology, successful boards must balance “playing offense” (investing in growth and pursuing strategic opportunities) with “playing defense” (ensuring risk oversight and maintaining operational stability). In this regard, as one executive noted to us in the writing of this report, “Every board is out of balance one way or the other.” And so, every company needs a playbook that meets its unique circumstances.
This publication offers a way to craft that playbook, and to help company directors establish strategic, differentiated, long-term governance, drawing on perspectives and examples from public and private companies around the world:
- Questions for Developing Strategic Governance
- Self-Assessment for Board Directors
- Pro Tips for Board Chairs
The critical insight for board governance is that any position on the spectrum, from defensive risk minimization to offensive growth orientation, can support long-term value creation when appropriately aligned with the company’s circumstances. The key determinant of success is not adopting a particular governance style but rather establishing and actively maintaining alignment between the board, management, and strategic objectives as conditions evolve.
Part I: Balancing Offense and Defense
Boards both support management through disruption and must challenge management to generate value and manage risk. In this sense, high-performing companies tend to find a good balance between defense and offense.
Yet, despite the importance of this balance, executives have told us that nearly every board struggles to achieve this equilibrium, “and it’s the CEO’s and chair’s job to constantly seek it.”1
This conclusion recalls findings from Corporate long-term behaviors: How CEOs and boards drive sustained value creation, prior FCLTGlobal research conducted in partnership with McKinsey & Company. That work found that many established businesses have developed an aversion to risky bets. Instead of playing to win, they play not to lose—and so they struggle to stay in front of competitors. Accordingly, the long-term behavior for these companies is going on offense by investing sufficient capital and talent in large, risky initiatives to achieve a winning position. Yet companies must mind their defensive position at the same time: “Growth alone won’t deliver value.”2
A company’s strategy drives this balance, as expressed by its choice between evolutionary (i.e., incremental) and revolutionary (i.e., transformational) innovation, its risk appetite relative to growth objectives, and the type of relationship the board has with management. Whether public or private, firms may make quite different choices in these dimensions.
We have synthesized these dimensions and identified where typical companies fall on this spectrum, using direct input from a wide variety of investors and corporations.
Exhibit 1. Evaluating the balance between a board’s offense and defense
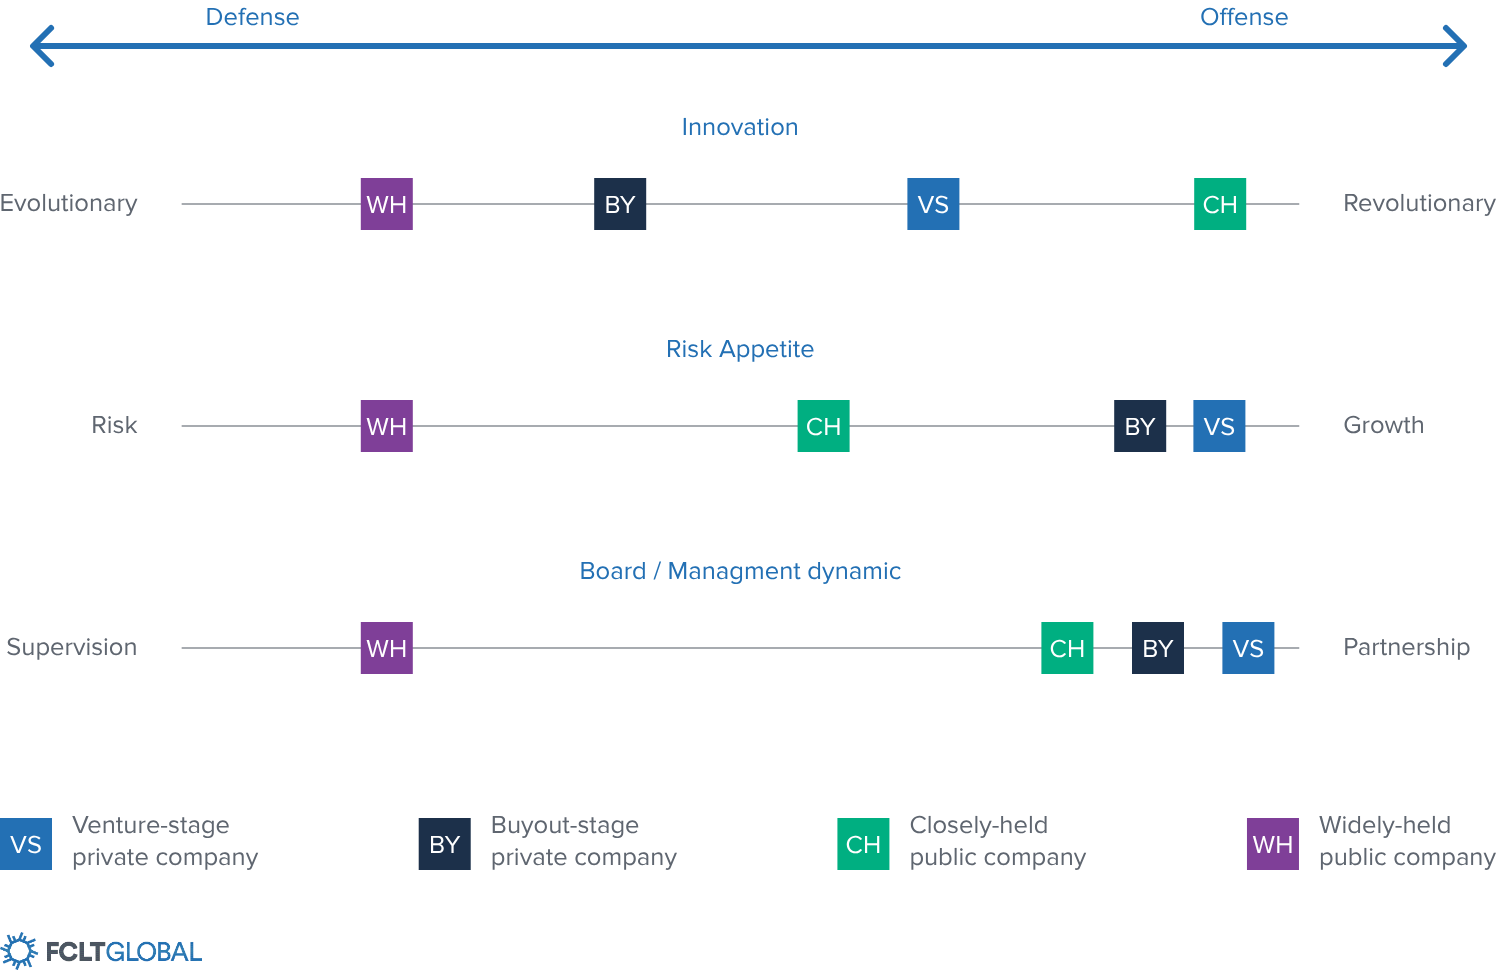
From these discussions, we conclude that:
- Boards of widely held public companies tend to have more evolutionary, risk-averse, and supervisory-focused governance than their closely held and private market peers.
- In contrast, boards of more closely held companies, commonly in the form of family or founder-held firms, permit a long-term orientation alongside an increased focus on management as well as the ability to target the controlling shareholders’ risk appetite.
- Private equity boards are often more transaction-oriented with an intermediate time horizon.
- Meanwhile, venture capital boards tend to be revolutionary, growth-focused, and more involved in management as befits the needs of startups.3
These archetypes bring to life why different “playbooks” are right for different companies.
Board practices across these dimensions vary between companies across borders, just as they do between public and private companies. Notable differences can be observed in terms of shareholder involvement in board selection and director compensation.
- For instance, in the U.S., large shareholders are typically excluded from board selection, while in Sweden, large shareholders are asked to play a critical nominating role.
- In the U.K. and Europe, directors are often compensated with annual cash payments, while equity as part of director compensation is standard in the U.S.
What matters is that companies make choices that align with their circumstances and corporate strategy, and that their board and executive team are aligned with these choices.
Examples:
Votorantim: “At Votorantim, we have a clear and defined mandate that is always developed jointly with the board and shareholders. This mandate determines our strategic objectives, the level of risk we are willing to undertake, and the tools and incentives management has at its disposal… clear communication of these instruments in a smooth and frictionless manner ensures that the balance between long and short term, risk and growth, and management and governance can perpetuate throughout the company and its investments, becoming an inseparable part of the DNA and corporate culture. Ultimately, the goal is to make these balances ingrained in the company’s culture, beyond written and well-communicated policies.” 4
State Street: “The three critical requirements of a successful board are: a deep understanding of long-term strategy; CEO selection and succession planning; and effective risk oversight… Change is perhaps the only constant in business. As new opportunities, challenges, and risks present themselves, skill sets must never remain stagnant. This holds true especially at the board level. New ways of supporting corporate boards — and enabling individual board members to evolve through deeper corporate understanding and subject matter expertise — are essential components of delivering upon any company’s long-term strategic goals.” 5
Part II: Learning from Best Practices Across Geographies and Markets
Boards can draw on the practices of long-term companies from around the world, across both public and private markets, to establish their own differentiated, strategic governance. As stated previously, these practices pertain to the company’s strategic time horizon, appetite for growth relative to risk, and the board’s relationship with management.
Strategic Time Horizon Practices
These include the company’s investment horizon, directors’ compensation structure, and the term lengths of directors.
A long-term board aligns its time horizon with the company’s investment horizon. The length of a company’s strategic focus may vary based on its industry or product cycle, meaning one time horizon does not fit all companies. A mismatch between the board’s time horizon and that of the company can hinder the board’s long-term success.
To assess alignment, compare the company’s investment horizon with directors’ compensation and term lengths. This alignment is easier to track across different stages of company growth (e.g., private ventures versus mature, widely held public firms). However, national regulations and market practices may impact the feasibility of aligning time horizons, as countries do not have uniform investment horizons for their corporations.
Risk and Growth Practices
These practices involve the board’s mindset, incentives, and aspirations, which are shaped by both intrinsic and extrinsic motivations.
Long-term boards ensure that directors’ motivations align with the company’s strategy. Conflicting motivations can undermine long-term success. Monetary incentives, such as equity or options, often encourage directors to focus on growth, while fixed instruments like cash can motivate risk control. However, directors’ personal aspirations also influence their approach. For example, a director in a family-owned company may prioritize long-term growth, while a supervisory director in Germany may focus on oversight due to labor representation.
Partnership and Supervision Practices
These practices define the board’s relationship with management, particularly in terms of focus and representation.
A board’s priorities influence its culture, access to information, and interactions with management. Smaller boards, often more agile, may prioritize investor perspectives and work closely with management. In contrast, larger boards, which inherently represent more diverse perspectives, may adopt a more deliberative approach, which can make them less nimble.
The size of the board can affect its ability to partner closely with management. In ventures or companies undergoing turnarounds, clear vision and commitment that smaller boards often offer are essential for long-term success. Larger boards, though less agile, often are better suited for the deep deliberation needed to help more established businesses thrive in future generations.
The following matrix catalogs practices of boards across the aforementioned ownership structures. Another matrix that immediately follows does the same in various national markets but focuses just on widely-held public companies out of necessity, since practices across ownership structures vary widely even within countries. These are meant to serve as an illustrative menu of options for boards to choose from, rather than a precise characterization of any single governance system. We emphasize that these practices are not prescriptive and are subject to wide variation.
| Private | Public | |||
| Characteristics | Venture | Buyout | Closely-held (Founder, Family) | Widely-held |
| Strategic Horizon | ||||
| Investment horizon | 5-7y | 3-5y | Generational | 3y |
| Payday target | Public market IPO or strategic sale | Sale of the company | Intergenerational | Vesting and lockup horizons |
| Term length | At the board’s will | Until exit | 1y with exceptions | Unlimited, 1-yr renewal with adversarial exception |
| Growth Driven – Risk Focused | ||||
| Incentives | ||||
| Reward | Equity and Options | Equity | Permanent Equity | Base + Equity |
| Constraint | Time to fix, Next deal | Next fundraising ability | Family Reputation | Personal Reputation |
| Aspiration | ||||
| Emphasis | Build the future | Operational effectiveness | Prestige | Insight, oversight, foresight |
| Core Lever | Strategy | Expertise | Professional management | Consultation |
| Partnership – Supervision | ||||
| Focus | ||||
| Board culture | Visionary | Near-term return | Grounded | Aligned |
| Engagement distance | High involvement | High involvement | Moderate involvement | Limited involvement |
| Information availability | Full access | Full access | Need to know basis | CEO curated |
| Information analysis, synthesis | Fully resourced | Fully resourced | Resource limited | Resource-limited, boardroom only |
| Meeting frequency | Weekly | Ad hoc | Monthly | Quarterly |
| Representation | ||||
| Board size | 6 | 6–8 | Variable | 12–14 |
| Diversity | Low | Low | Variable | Medium |
| Investor | Yes | Yes | Yes | No (Ex. activists) |
| Independent | No | No | Variable | Yes |
| Workforce representation | No | No | No | No |
| Characteristics | United States | United Kingdom | Sweden | Germany (Supervisory tier) | Japan |
| Strategic Horizon | |||||
| Payday target | Long-term ownership incentives with vesting and lockup horizons | Annual (cash) | Annual (cash) with some long-term ownership incentives | Annual (cash) | Annual (cash); evolving to some equity long-term ownership incentives |
| Term length | No legal tenure limit; 1y terms with adversarial exceptions | 9y independent tenure limit; 1-3y terms | Varies by whether the director represents a block holder | No legal tenure limit; 3-5y terms | No legal tenure limit; 1y terms with adversarial exceptions |
| Growth Driven – Risk Focused | |||||
| Incentives | |||||
| Rewards | Base, equity | Base, prestige, service | Relationships, Honoria cash secondarily | Prestige; Honoria cash secondarily | Base, equity evolving; low absolute levels of compensation |
| Constraints | Personal Reputation | Sense of liability and personal reputation | Structural boundary of AGM-board and of board-management | Limited scope of influence | Expectation of consensus internally; Personal reputation and some liability externally |
| Aspirations | |||||
| Emphasis | Insight, oversight, foresight | Oversight, direction-setting | Insight, oversight, foresight | Oversight | Trust, support, allegiance |
| Core Lever | Consultation | Disclosure | Agenda setting | Meetings, including committees | Support of the CEO |
| Partnership – Supervision | |||||
| Focus | |||||
| Board culture | Maximize shareholder value | Balanced for stakeholder considerations | Shareholder value first, stakeholder considerations second | Focused on stakeholder (i.e., employee) considerations | Consensus-oriented |
| Engagement distance | Limited involvement | Limited involvement | Limited involvement | Moderate involvement | High involvement |
| Information availability | CEO curated | Exhaustive disclosure | Broad access to management | Via the management board | CEO curated |
| Information analysis, synthesis | Resource-limited, boardroom only | Resource-limited, boardroom only | Hired advisors | Expectations of supervisory directors | Procedural and technical |
| Meeting frequency | Quarterly + committee meetings | Quarterly + committee meetings | 5-8 times/year | >8 times/year + committees | Monthly |
| Representation | |||||
| Board size | 11-14 | 10-12 | 6-12 | 15-20 | 10-15 |
| Diversity | Medium | Medium | Medium | Medium | Lower but accelerating |
| Investor | Low | Low | High for the nominating committee; low for the board | High | High |
| Independent | Yes | Yes | Yes | Yes | Yes, for globally competitive companies; Low for domestically competitive companies |
| Workforce representation | No | No | Yes | Yes | No |
“Recap: FCLT Summit 2024,” FCLTGlobal, 07 March 2024, pg. 7: https://www.fcltglobal.org/resource/recap-fclt-summit-2024/.
Sneader, Kevin, Sarah Williamson, Tim Koller, and Victoria Potter. “Corporate long-term behaviors: How CEOs and boards drive sustained value creation,” FCLTGlobal and McKinsey & Co, 1 October 2020, pp. 6-7:
Leatherman, Matt and Jess Gaspar. “The Myth of the One Size Fits All Board”, FCLTGlobal, 15 April 2024:
João Schmidt, CEO of Votorantim
O’Hanley, Ronald. “Maintaining board skills to ensure long-term success,” in “2024 Blue Book: A Blueprint for the Long Term,” FCLTGlobal, February 2024, pp. 64-65:
“Future Fit Boards: Questions For Developing Strategic Governance,” 17 June 2024:
Canet, Antoine, “Groupthink in the Boardroom – The Good, the Bad and the Ugly”, 10 June 2016:
Benabou, Roland. “Groupthink: Collective Delusions in Organizations and Markets”. The Review of Economic Studies, Volume 80, Issue 2, April 2013:
Babcock, Ariel, et al. “Tone at the Top: The Board’s Impact on Long-term Value,” FCLTGlobal and Russell Reynolds, 23 April 2020: https://www.fcltglobal.org/resource/tone-at-the-top-the-boards-impact-on-long-term-value/.
“Going for Gold — The 2019 Global Board Culture and Director Behaviors Survey,” Russell Reynolds, 15 April 2019:
Babcock at al, “Tone at the Top.”
Yu, Mei. “CEO duality and firm performance: A systematic review and research agenda,” The Journal of the European Academy of Management, 25 May 2022:
Fernandez-Araoz, Claudio, Gregory Nagel, and Carrie Green. “The High Cost of Poor Succession Planning,” Harvard Business Review, May-June 2021:
Babcock et al, “Long-term Habits.”
Sneader et al, “Corporate Long-term Behaviors,” pg. 8.
Babcock, Ariel, Allen He, and Victoria Tellez. “Driving the Conversation: Long-Term Roadmaps for Long-Term Success,” FCLTGlobal, 21 February 2019:
Paula, Joel, Matt Leatherman, Sarah Williamson, and Jess Gaspar. “The CEO Shareholder: Straightforward Rewards for Long-term Performance,” FCLTGlobal, 26 September 2023:
Sneader et al, “Corporate Long-term Behaviors,” pg. 8.
Leatherman, Matt, Victoria Tellez, Ariel Babcock, and Matt Brady. “The Risk of Rewards: Tailoring Executive Pay for Long-term Success,” FCLTGlobal, 08 March 2021: https://www.fcltglobal.org/resource/executive-pay/.
Babcock et al, “Long-term Habits.”
Petersen, Randall, and Gardner, Heidi, “Is Your Board Inclusive — or Just Diverse?”. Harvard Business Review, 2021:
Akimoto, Mary, et al. “Board Diversity and Effectiveness in FTSE 350 Companies,” London Business School, SQW, and Financial Reporting Council, July 2021:
Babcock et al, “Long-term Habits.”


